Dubai property for Indian buyers: the LRS and NRI routes explained.
How you fund a Dubai purchase from India depends entirely on your residency status. Resident Indians move money out under the RBI's Liberalised Remittance Scheme, which caps the amount and triggers a 20% tax collected at source above a fairly low threshold. NRIs generally don't touch LRS at all — they fund purchases from their own NRE or NRO accounts, under a different set of rules entirely.
This guide separates the two routes clearly, since conflating them is where most confusion — and most avoidable tax cost — comes from.
- Resident Indians: USD 250,000/year via LRS, 20% TCS above ₹10 lakh
- NRIs: fund from NRE/FCNR or NRO accounts — LRS and TCS don't apply
- TCS is refundable/adjustable against your final Indian tax liability
- Funds must be traceable — no cash, credit card, or India-sourced loan
- Resident-owned foreign property must be disclosed annually (Schedule FA)
The LRS route and 20% TCS
Resident Indians can buy Dubai property under the RBI's Liberalised Remittance Scheme — but property sits in the higher-taxed "investment" category, not the lower rate that applies to education or medical remittances.
| Detail | |
|---|---|
| Annual limit | USD 250,000 per individual, per financial year (April–March), combined across all LRS purposes |
| TCS-free threshold | ₹10 lakh per financial year, cumulative across all remittances (PAN-based) |
| TCS rate above threshold | 20% — the standard investment-category rate, not the lower 2% rate for education/medical |
| Refundable? | Yes — TCS reflects in Form 26AS and can be offset against your final tax liability, or refunded if you have none |
What LRS actually requires
Funds must come from your own account through an authorised dealer bank wire — not cash, not a credit card, and not a loan taken in India.
Once purchased, the property must be disclosed in your Indian tax return every year you hold it, under the Foreign Assets schedule.
Sale proceeds generally need to be brought back to India under FEMA rules for resident-held foreign property — plan the exit alongside the purchase, not after.
The NRI route: NRE, FCNR, and NRO funds
NRIs don't use LRS to fund an overseas purchase — LRS applies to resident individuals remitting money out of India, and NRIs are, by definition, not resident. Instead, NRIs typically fund a Dubai purchase from an NRE (Non-Resident External) or FCNR account, both freely repatriable, or from an NRO (Non-Resident Ordinary) account holding India-sourced income.
NRO account repatriation is capped at USD 1 million per financial year and requires a chartered accountant's certification (Form 15CA/15CB) confirming taxes have been settled on the underlying funds before they leave India.
- NRE / FCNR accounts: freely repatriable, no LRS or TCS applies
- NRO accounts: capped at USD 1 million per year, needs Form 15CA/15CB from a CA
- Foreign income held abroad: no Indian remittance mechanics apply at all if never brought into India
Ongoing Indian tax exposure
| Resident Indian | NRI | |
|---|---|---|
| Dubai rental income | Taxable in India as worldwide income | Generally outside Indian tax scope — India taxes NRIs only on India-sourced income |
| Capital gains on sale | Taxable in India | Generally outside Indian tax scope |
| Annual disclosure | Required (Schedule FA) | Not applicable for foreign assets held while non-resident |
Sizing a purchase against the LRS limit
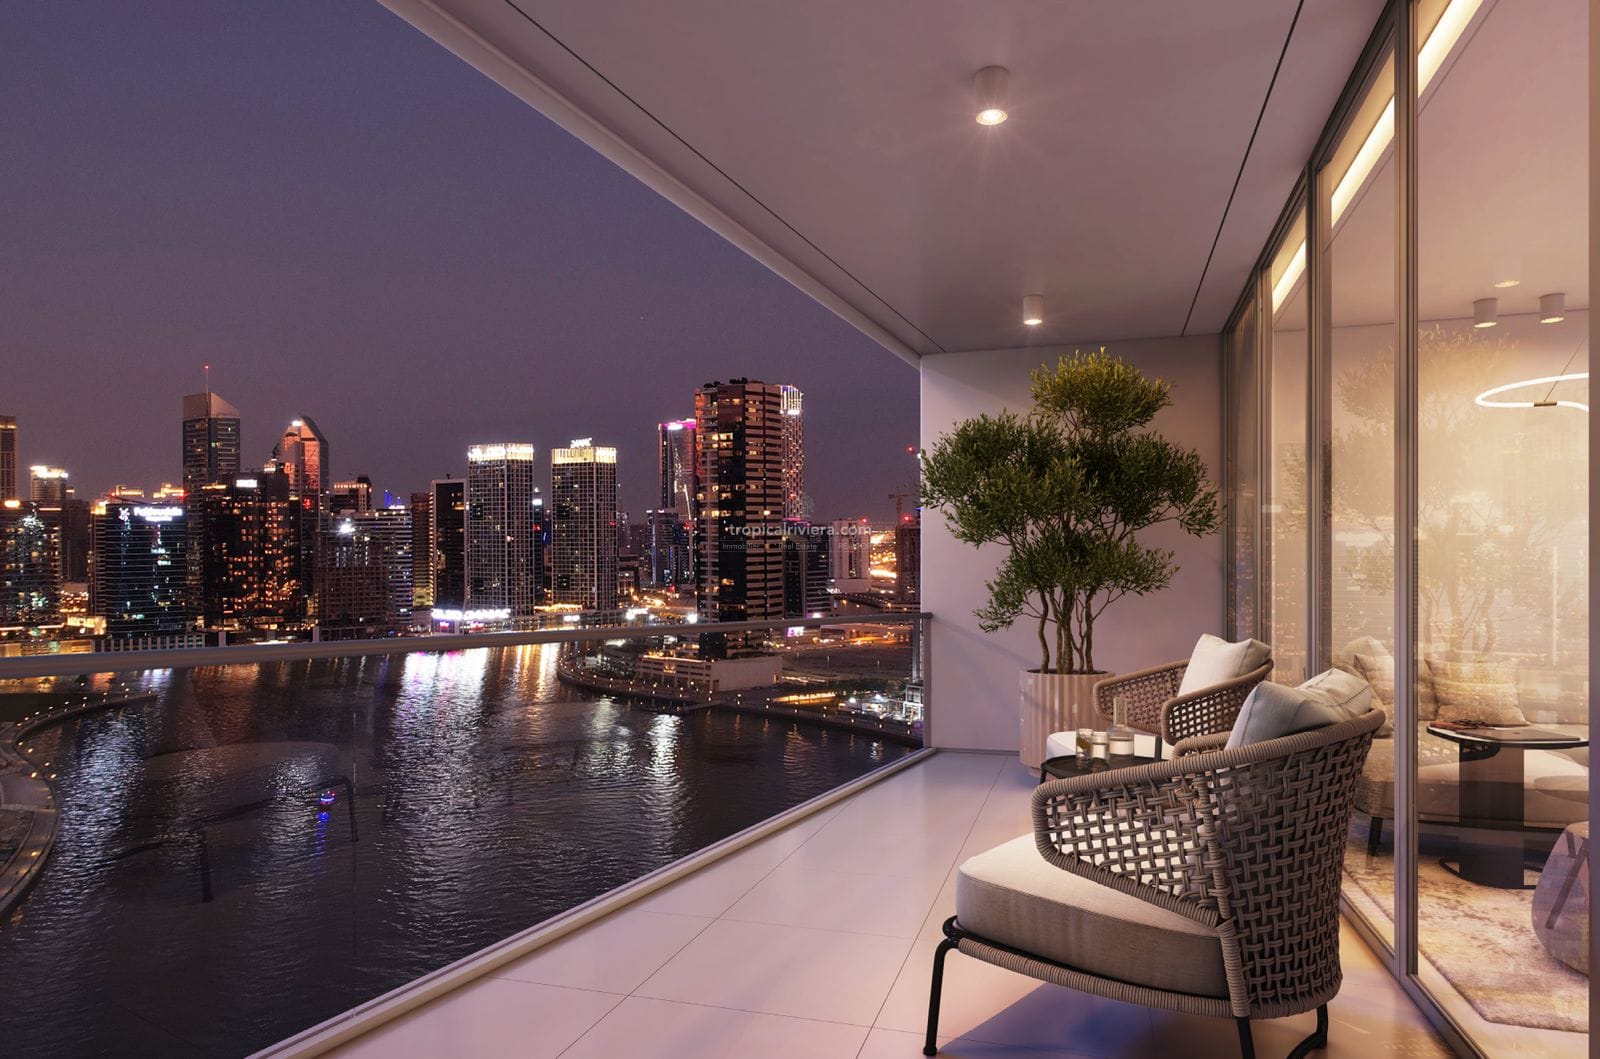
Within a single year's LRS limit — DG1 Living
A resident Indian buyer can typically fund a unit at this price point within a single financial year's USD 250,000 LRS allowance, without needing to plan the remittance across multiple years.
Above a single year's limit — DaVinci Tower by Pagani
At this tier, a resident Indian buyer may need to spread remittances across two financial years to stay within the LRS cap, or use joint family allowances (each adult family member has their own USD 250,000 limit) — plan this into the payment schedule with the developer in advance.
Once funds have cleared, the Dubai purchase process itself is the same as for any international buyer. See our Dubai investment guide, the Dubai ownership framework, and our source of funds guide for what UAE banks and the DLD will separately want to see about the same transfer.
A licensed international advisory built on formal professional standards
Tropical Riviera International Realty is a licensed international real estate advisory. Bhavesh Koonja, our principal broker, holds both the REALTOR® and Certified International Property Specialist (CIPS) designations through the National Association of REALTORS® — credentials that carry a formal code of ethics and fiduciary standard, not just a sales licence, and that apply to how we advise wherever we practice internationally.
We coordinate the Dubai side of the transaction for Indian buyers, both resident and NRI, and work alongside your chartered accountant on the LRS, TCS, and FEMA questions that sit outside our own expertise. See our International Real Estate overview and International Real Estate Advisory approach for how this fits our wider ten-market coverage.
WhatsApp Us Now (+230 5256 5725)- REALTOR® — National Association of REALTORS®
- Certified International Property Specialist (CIPS) — NAR designation
- Bilingual — English and French advisory
- Ten markets served — Mauritius, Oman, UAE, Qatar, Saudi Arabia, Spain, Bali, Zanzibar
Dubai property for Indian buyers FAQ
How much can a resident Indian remit to buy Dubai property?
Up to USD 250,000 per financial year under the Liberalised Remittance Scheme (LRS). Larger purchases typically need to be spread across financial years or funded jointly by multiple family members, each with their own USD 250,000 limit.
What is the TCS rate on money sent to buy Dubai property?
20% on the amount above ₹10 lakh per financial year, since overseas property falls in the higher-taxed "investment" category rather than the lower 2% rate that applies to education or medical remittances. TCS is refundable or adjustable against your final Indian tax liability.
Do NRIs need to use LRS to buy Dubai property?
No. LRS applies to resident Indians remitting money out of India. NRIs typically fund a purchase from their own NRE, FCNR, or NRO accounts, and are not liable for TCS on those transfers.
How much can an NRI repatriate from an NRO account?
Up to USD 1 million per financial year, subject to a chartered accountant's certification (Form 15CA/15CB) confirming applicable Indian taxes on the underlying funds have been settled.
Do I need to declare my Dubai property on my Indian tax return?
If you're a resident Indian, yes — foreign property must be disclosed annually under the Foreign Assets (Schedule FA) section of your return for every year you hold it. This generally doesn't apply to NRIs for property held while non-resident.
Plan your remittance alongside your purchase
Tell us whether you're a resident Indian or NRI and your target budget, and we'll walk through how the funding route lines up with the Dubai purchase timeline.
WhatsApp — Start the Conversation